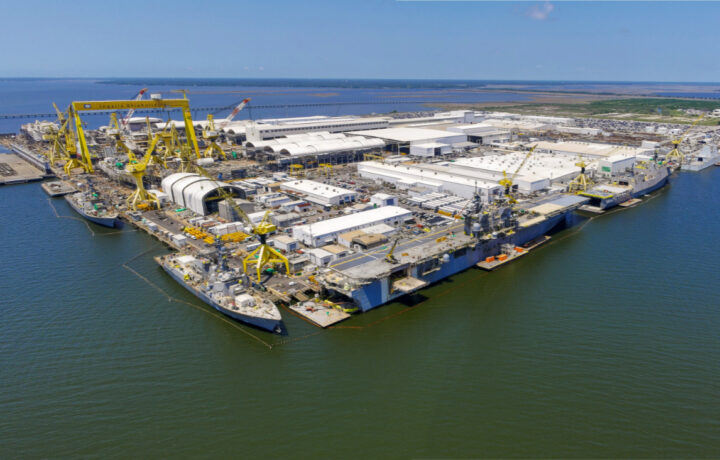
Huntington Ingalls (HII) stock has continued to struggle in recent months, as many on the Street fret about the company’s negative free cash flows in the first two quarters of the year. But these losses appear to stem from the large investments HII is making to fulfill the major shipbuilding contracts it has received from the U.S. Navy.
Over the longer term, the company’s spending will drop, and more contract funds will flow to Huntington, boosting cash flow. Indeed, this process is already beginning, as the company expects to generate positive free cash flow in the third quarter, the fourth quarter, and throughout 2026.
Meanwhile, it recently obtained more shipbuilding contracts, and its core shipbuilding business continues to thrive. Also noteworthy is that its unmanned surface vessel program, Romulus, remains well positioned to become a needle-moving new growth driver for the company. Finally, because of Wall Street’s short-sightedness, Huntington Ingalls’ valuation is extremely low. In light of these points, HII stock appears to be a great pick for value investors and growth-at-a-reasonable-price investors.
Falling Stock Amid Negative Cash Flows, But the Picture Will Improve
Huntington’s free cash flows came in at -$150 million and -$464 million in Q2 and Q1, respectively. But its investing cash flows rose to -$118 million and -$71 million in those quarters. Conversely, its investing cash flows for the same quarters in 2025 were -$92 million and $0, respectively.
Further, its capital spending rose to $193 million in the first half of 2026 versus $160 million during the same period a year earlier. Moreover, as of last November, the company had hired more than 4,600 additional shipbuilders in 2025, and as of July 30, it had added more than 3,500 such employees in 2026. All of these metrics indicate, as I noted earlier, that the firm is investing more funds to fulfill its previous ship orders.
As mentioned earlier, the situation should improve as the company’s investments drop and more revenue from its contracts starts flowing in. Supporting that view, Huntington expects positive free cash flow of $100 million for the current quarter and “significant free cash flow generation in the fourth quarter,” enabling free cash flow for the year to come in at $500 million to $600 million.
Additional Shipbuilding Contracts and a Thriving Shipbuilding Business
In July, the firm disclosed that it had obtained “contracts for (the) construction of Block VI Virginia-class and Build II Columbia-class submarines.” The deals will total $76.6 billion, according to Huntington.
In Q2, the revenue of the company’s shipbuilding unit jumped an impressive 15.7% versus the same period a year earlier to $2.7 billion. The unit’s operating income rose to $169 million, up from $136 million in Q2 2025.
Overall, last quarter, Huntington’s revenue climbed 10.9% year over year to $3.4 billion, while operating income rose to $210 million in Q2 versus $163 million during the same period a year earlier.
Romulus Looks Poised To Excel, and the Valuation of Huntington Stock Is Very Low
After America’s inability to protect shipping in the Strait of Hormuz, the Navy is looking to obtain a significant number of unmanned surface vessels (USVs). On Huntington’s Q2 earnings call, CEO Christopher Kastner noted that Romulus, Huntington’s USV, had been chosen to take part in Navy tests slated for September.Given the firm’s extensive contacts with the Navy, its vast shipbuilding experience, its ability to spend heavily on Romulus R&D, and the ships’ autonomous capabilities, I expect Huntington to capture a large share of the significant amounts the Navy is likely to spend on USVs.
Huntington is trading at an extremely low forward P/E ratio of 13.
*This article is intended to be informational only; it is not financial advice.


