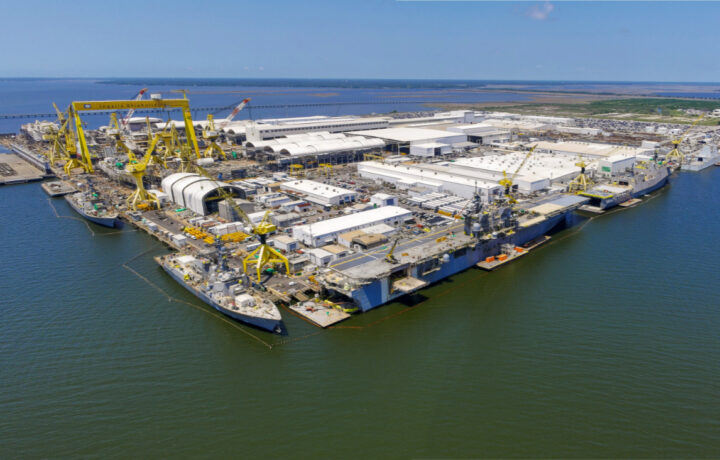
Driven by Huntington Ingalls’ (HII) rapidly expanding core shipbuilding business, the company reported outstanding third-quarter financial results on October 30. Meanwhile, the company has recently secured several significant, encouraging contracts, and Goldman Sachs is very bullish on HII stock. Finally, Huntington’s valuation remains quite attractive.
In light of these points, long-term value investors should consider buying the shares.
Shipbuilding Drives Impressive Overall Earnings
In Q3, Huntington’s shipbuilding revenue advanced 13.9% versus the same period a year earlier to $2.8 billion, representing 80% of its total sales. The company’s Newport News facility generated increased revenue from its submarine and aircraft carrier development.
Overall, Huntington’s top line climbed 10.8% year over year to $3.54 billion, and net earnings soared 50% compared with Q3 2025 to $217 million.
And there’s every reason to believe that the company’s shipbuilding business will continue to thrive for years to come. “With approximately 90% of expected shipbuilding revenue through 2030 already under contract, our focus is squarely on execution, growing our workforce, improving throughput, and delivering the ships and technologies our nation needs,” CEO Chris Kastner said on the company’s Q3 earnings call.
Encouraging Contract Wins and a Promising New Product
In August, the firm obtained a $2.2 billion contract from GSA. Under the deal, the company’s Missile Technologies unit will perform surveillance, tracking, reconnaissance, analysis, and interception services. As a result, it will “enhance SOUTHCOM’s ability to detect, monitor, and disrupt illicit activity across Central America, South America, and the Caribbean.”
Also in Q3, Huntington landed a major deal to provide unmanned underwater vessels (UUVs) to the Navy, and it will provide ten of its Romulus unmanned surface vessels (USVs) to the service branch. At a time when the Navy is likely looking for a way to counter Iran’s attacks in the Strait of Hormuz, these deals bode well for Huntington’s ability to keep helping on this issue.
Meanwhile, the firm also recently showcased an “end-to-end autonomous mine countermeasure” system it developed in tandem with another company, Thales. Of course, the product can be quite useful in Hormuz, where Iran has placed a significant number of mines.
Goldman’s Strong Recommendation and the Low Valuation of HII Stock
On October 30, Goldman Sachs reiterated a Conviction Buy rating and a $406 price target on HII stock. According to the investment bank, the firm’s reported higher-than-expected Q3 profit margins, while its free cash flow also came in above analysts’ average estimate last quarter. Moreover, the investment bank believes the company should benefit from continued revenue growth going forward. Most impressively, Goldman said HII’s EPS could roughly double between 2026 and 2030.
Despite Huntington’s strong growth, multiple positive drivers, and powerful outlook, its shares are changing hands at a very low forward price-earnings ratio of 14.4 times and a tiny price-to-sales ratio of 0.9 times.
*This article is intended to be informational only; it is not financial advice.


