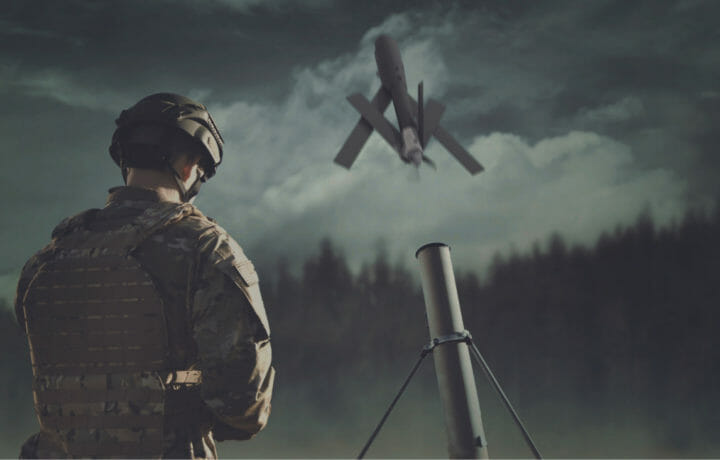
AeroVironment (AVAV) is making commendable progress marketing its anti-drone products, as noted in my previous column on AVAV stock. Meanwhile, it reported impressive first-quarter financial results in September, and its valuation has become much more reasonable in 2026. Finally, over the last few months, the company has secured multiple contracts and signed two partnerships with strong potential.
In light of these points, growth investors should consider buying AVAV stock.
Meaningful Progress on Marketing Its Anti-Drone Systems
AVAV received a roughly $465 million contract in late August to provide Locust, its anti-drone laser system, to the U.S. Army. Later, the firm announced it had received an order for Locust from a foreign country.
Additionally, a U.S. Joint Interagency Task Force agreed to spend $500 million on another one of AVAV’s counter-drone products, Titan. The latter system uses RF jammers to counter drones.
As I’ve noted previously, the U.S., Israel, and multiple other nations urgently seek affordable means of combating enemy drones. In the earlier column, I asserted that AVAV appeared to be “well-positioned” to benefit from this “rapidly growing demand for anti-drone solutions.” With the company now a first mover in the space, that process appears to be underway.
Also bullish on AeroVironment’s outlook in the anti-drone space is investment bank Clear Street. After meeting with AVAV’s CFO, Clear Street asserted that the $465 million award from the Army “is an early indication of what could become a larger procurement cycle, as U.S. services and international customers add directed energy to the counter-UAS stack,” Investing.com reported.
Strong Q1 Results and a Much More Attractive Valuation
Very impressively, in AeroVironment’s fiscal first quarter that ended on August 1, its “funded backlog” soared 37% versus the same period a year earlier to $1.5 billion, while its book-to-bill ratio came in at a high 1.4 times. These metrics strongly indicate that the company’s growth is poised to soar tremendously in the medium-to-long term.
On the valuation front, AVAV stock as of October 14 was changing hands at a forward price-earnings ratio of 55, down from 70.4 and 200 in January and October 2025, respectively. What’s more, its price-sales ratio has shrunk to 3.9 times from 5.3 in April, 7.7 in January, and 11.2 last October.
Very Promising Contracts and Partnerships
AeroVironment and Taiwan-based Thunder Tiger agreed to a memorandum of understanding, under which they will assess the feasibility of cooperating on “unmanned systems integration and potential co-production in Taiwan.” Specifically, they will try to add AVAV’s Switchblade system to Thunder’s “unmanned surface and ground platforms.” The deal could give the U.S. firm significant new revenue opportunities in Taiwan and, eventually, elsewhere, as it will likely receive royalties on sales of Thunder’s products that use Switchblade.
Meanwhile, AeroVironment unveiled an MOU that may lead to integrating Alpha’s offerings, including the latter firm’s ground control station and tracking system, into AVAV’s vertical takeoff and landing (VTOL) aircraft. If Alpha’s systems meaningfully improve AVAV’s products, they could significantly boost AVAV’s sales.
Turning to drone contracts, AeroVironment secured a $117 million deal from the Army for its P550 drones in July, along with a $51 million deal for its Switchblade drones.
*This article is intended to be informational only; it is not financial advice.


